403(b) or 457(b) to Gold IRA: Rollover Rules for Teachers and Public Employees (2026)
A 403(b) to gold IRA rollover works differently from a 401(k) rollover. Teachers, hospital and nonprofit staff, and state and local government workers usually save in a 403(b) or a 457(b), not a 401(k). Both can be moved into a self-directed gold IRA without taxes, but one kind of 457(b) cannot be moved at all, and a governmental 457(b) has a penalty-free feature you lose when you leave it. Here is how it works.
The short answer
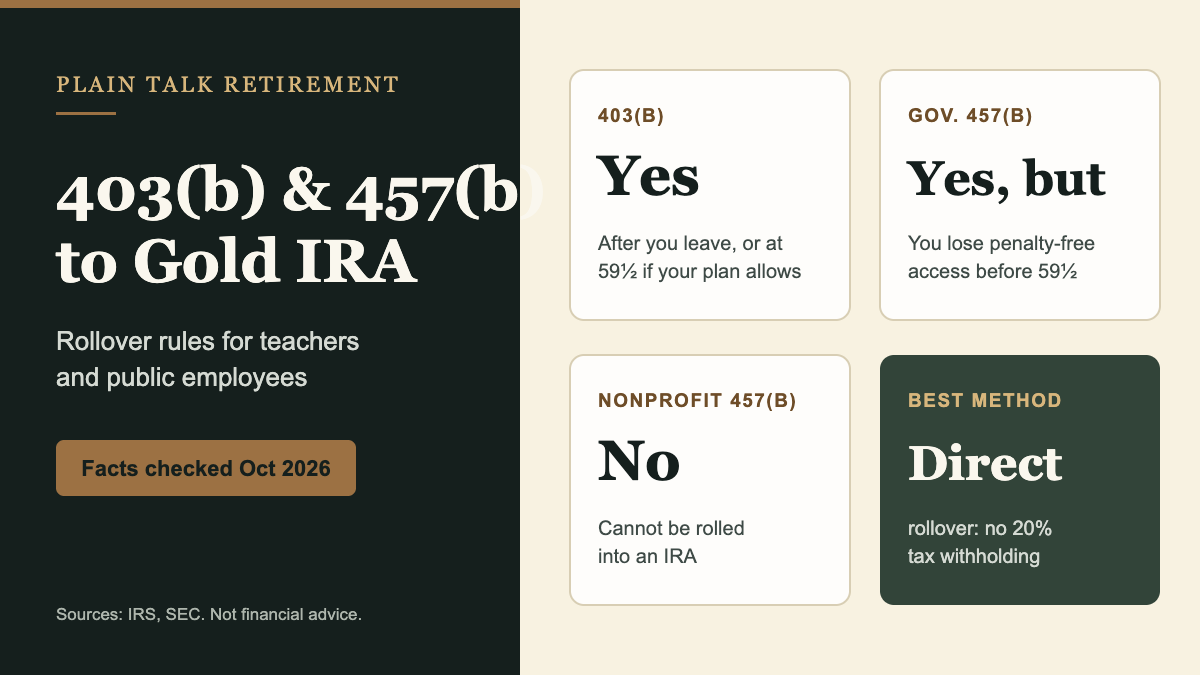
- A 403(b) can be rolled into a gold IRA once your plan allows a distribution, usually after you leave your job or reach 59½.
- A governmental 457(b) can too. A 457(b) from a tax-exempt nonprofit cannot be rolled into an IRA.
- Use a direct rollover so the plan pays your new IRA custodian and nothing is withheld for taxes.
- Check two costs first: annuity surrender charges in many 403(b) plans, and the governmental 457(b)’s penalty-free access, which ends once the money is in an IRA.
Which 403(b) and 457(b) money can go into a gold IRA?
The IRS sets the outer limits, but your plan’s own rules decide what it actually allows.
403(b), you have left the job
Yes. Leaving your employer allows a distribution you can roll into an IRA.
403(b), still working, 59½ or older
If your plan allows it. The IRS permits distributions at 59½; many plans offer in-service rollovers from that age.
Governmental 457(b)
Yes. After you leave your job, or from 59½ if the plan allows in-service distributions.
Tax-exempt (nonprofit) 457(b)
No. The IRS does not allow these to be rolled into an IRA.
Hardship withdrawals
No. Hardship distributions cannot be rolled over to any IRA.
Roth 403(b) or Roth 457(b)
Yes, to a Roth IRA. Roth money goes to a Roth IRA, pre-tax money to a traditional IRA.
Sources: IRS, 403(b) plan FAQs; IRS, Comparison of tax-exempt and governmental 457(b) plans; IRS, Rollovers of retirement plan and IRA distributions.
Not sure which 457(b) you have? If your employer is a state, county, city, school district or other public body, it is almost always governmental. If it is a private nonprofit such as a hospital or charity, ask HR, because that plan may be a tax-exempt 457(b).
The governmental 457(b) penalty trap
A governmental 457(b) has a feature almost no other retirement plan has: once you leave your job, you can take money out at any age without the 10% early distribution tax. You still pay income tax, but not the penalty.
That feature stays with the 457(b). If you roll the money into an IRA, including a gold IRA, withdrawals before 59½ can face the 10% tax unless another exception applies.
| Money taken out before 59½ | 10% early distribution tax? |
|---|---|
| From a governmental 457(b) | No (except money you rolled into the 457(b) from another type of plan or IRA) |
| From an IRA, after a 457(b) rollover | Yes, unless another exception applies |
| From a 403(b), after leaving your job in or after the year you turn 55 | No (age 50 for many public safety employees) |
Sources: IRS, Exceptions to tax on early distributions; IRS Notice 2026-13, Safe harbor explanations for eligible rollover distributions.
The practical takeaway: if you are under 59½ and might need this money soon, keep enough in the 457(b) (or the 403(b), if you left at 55 or later) to cover it, and move only the rest.
403(b) annuity surrender charges
Many 403(b) plans, especially for teachers, hold annuity contracts from insurance companies rather than mutual funds. The SEC warns that if you withdraw money from an annuity within its first few years, the insurer may charge a surrender fee, usually a percentage of the amount that declines over several years.
Before you request a rollover, ask your 403(b) provider for the exact surrender charge in writing. If it ends soon, waiting can save real money. Mutual fund 403(b) accounts usually have no surrender charge.
Source: SEC Investor Bulletin: Retirement Investing Through 403(b) and 457(b) Plans.
How to move a 403(b) to a gold IRA, step by step
This is the direct rollover route, the one that keeps taxes out of it.
- Confirm what kind of plan you haveAsk HR or check your summary plan description: is it a 403(b), a governmental 457(b), or a tax-exempt 457(b)? Only the first two can be rolled into an IRA.
- Check when your plan allows a distributionMost plans pay out after you leave your job. Many also allow in-service distributions from age 59 1/2. Hardship distributions cannot be rolled over.
- Ask about surrender chargesIf your 403(b) holds an annuity, ask the provider for the exact surrender charge. It may be cheaper to wait until the charge ends.
- Open a self-directed gold IRAChoose a gold IRA company and open an account with its IRA custodian. Get the custodian's payee name, account number and mailing address for a direct rollover.
- Request a direct rollover from your planUse your plan provider's distribution form or website and choose a direct rollover to an IRA. The check should be made payable to your new custodian for your benefit, not to you, so no 20% is withheld.
- Choose your metalsOnce the money arrives, pick IRS-approved gold or silver bullion. It is shipped to an approved depository in your IRA's name. Get the price and markup in writing before you approve the purchase.
Direct rollover vs having the plan pay you
| What matters | Direct rollover | Paid to you first |
|---|---|---|
| Who the check is made out to | Your new IRA custodian | You |
| Federal tax withheld | None | 20% of the taxable amount |
| Deadline | None | 60 days to deposit the full amount in an IRA |
| If you miss it | Not an issue | The part not rolled over is taxed, and may face a 10% penalty |
Source: IRS, Rollovers of retirement plan and IRA distributions. To roll over the full amount after 20% was withheld, you would have to make up the difference from other savings.
6 mistakes to avoid
1. Moving a nonprofit 457(b)
A tax-exempt 457(b) cannot be rolled into an IRA. Any pitch that says otherwise is wrong.
2. Letting the plan pay you
A check made out to you triggers 20% withholding and a 60-day deadline. Always choose a direct rollover.
3. Ignoring surrender charges
An annuity surrender charge can cost more than a year of gold IRA fees. Get the number in writing first.
4. Rolling over all of a governmental 457(b) under 59½
You give up penalty-free access. Keep what you might need before 59½ in the 457(b).
5. Buying “rare” or collectible coins
They usually carry much bigger markups. Stick to IRS-approved bullion. See our gold IRA red flags guide.
6. Falling for home storage pitches
IRA metal must be held by the custodian or an approved depository. Keeping it at home can be treated as a distribution.
What a gold IRA costs after the move
Expect a one-time setup fee, yearly storage and custodian fees of roughly $225 at several major companies, and a dealer markup on the metal, which is usually the biggest cost. Gold also pays no interest or dividends. Our gold IRA fees guide breaks this down company by company. Moving a 401(k) or IRA instead? See our gold IRA rollover guide. Federal employees should read our TSP to gold IRA guide.
403(b) and 457(b) to gold IRA: frequently asked questions
Can I roll my 403(b) into a gold IRA?
Yes, once your plan allows a distribution. The IRS lets 403(b) plans pay out when you leave your job, reach age 59 1/2, become disabled or face a financial hardship, but your plan's own terms decide which of these it offers. Eligible distributions can go into a self-directed IRA that holds IRS-approved gold and silver. Hardship distributions cannot be rolled over.
Can I roll my 457(b) into a gold IRA?
Only if it is a governmental 457(b), the kind offered by state and local governments. Those can be rolled into an IRA after you leave your job, or from age 59 1/2 if your plan allows in-service distributions. A 457(b) from a tax-exempt nonprofit cannot be rolled into an IRA at all.
Will I lose anything by moving a governmental 457(b) into an IRA?
Possibly. Distributions from a governmental 457(b) are not subject to the 10% early distribution tax, even before 59 1/2. Once the money is rolled into an IRA, withdrawals before 59 1/2 can face that 10% tax unless another exception applies. If you may need the money before 59 1/2, consider moving only part of it.
Can I move my 403(b) while I am still working?
Only if your plan allows in-service distributions, which many 403(b) plans offer from age 59 1/2. Ask your plan administrator or HR office, or check your summary plan description.
Will I pay taxes on a 403(b) or 457(b) rollover to a gold IRA?
Not if you use a direct rollover, where the plan sends the money straight to your new IRA custodian. If the plan pays you instead, it must withhold 20% for federal income tax, and you have 60 days to deposit the full amount into an IRA or the missing part is taxed.
Does my 403(b) annuity charge a fee to move money?
It might. Many 403(b) plans hold annuity contracts, and the SEC warns that withdrawing from an annuity in its first few years can trigger a surrender charge that declines over several years. Ask your provider for the exact surrender charge before you request a rollover.
Can I roll a Roth 403(b) or Roth 457(b) into a gold IRA?
Yes, into a Roth IRA that holds precious metals. Roth money should go to a Roth IRA and pre-tax money to a traditional IRA, so you may need both kinds of self-directed IRA.
Get the rollover explained before anything moves
Augusta’s free Gold & Silver IRA Info Kit covers what to look for in a gold IRA company, and Augusta helps with most of the rollover paperwork. No pressure to buy.
Get the Free Gold IRA Info KitFor 403(b), 457(b), 401(k) and IRA balances of $50,000 or more.
Takes about 2 minutes · No purchase required